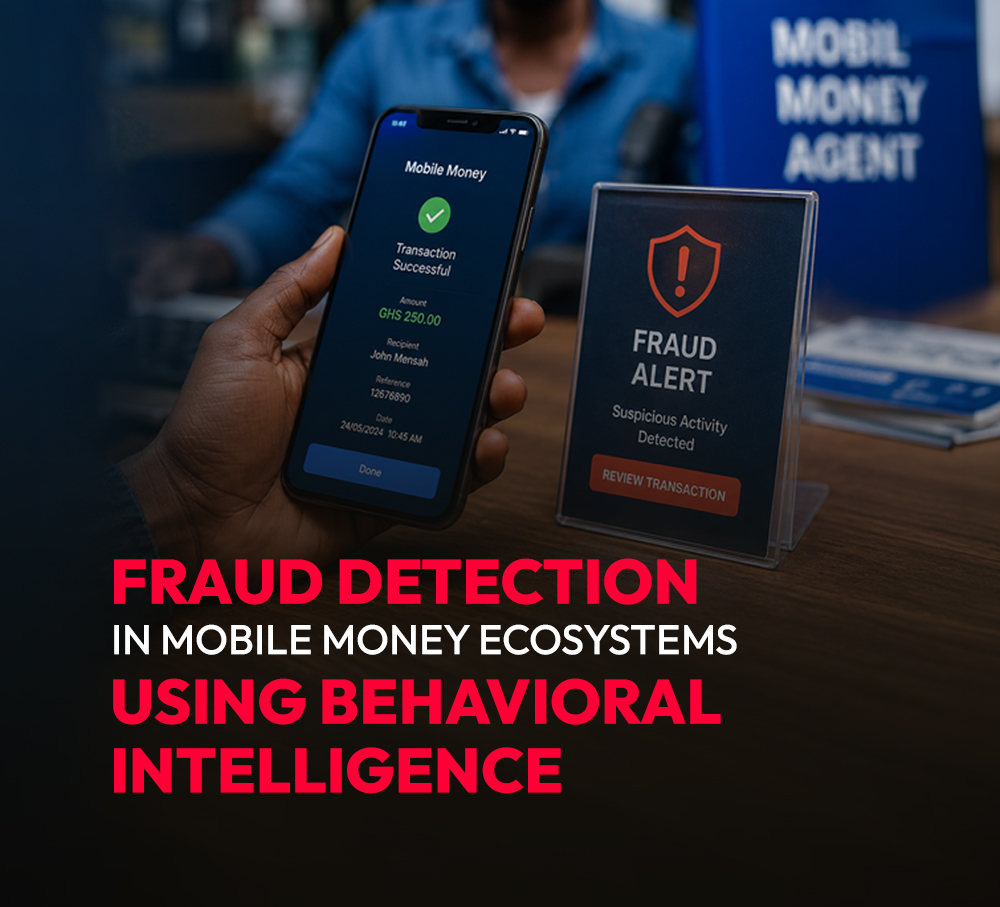
Kenya’s mobile money sector faces a massive disconnect between transaction volume and security. M-Pesa processed Sh6.5 trillion by September 2024, yet fraud losses surged 344% to Sh810 million. As the trending phenomenon “Mobile Banking Kenya” expands, static rule-based systems are failing against sophisticated attacks. The priority for institutions has shifted from basic upgrades to adopting behavioral intelligence capable of replacing predictable, legacy controls.
The Growing Fraud Risks in Mobile Money Ecosystems
Rising Mobile Payment Fraud Attempts
The FinAccess 2024 Survey reveals that 9.8% of Kenya’s mobile money users suffered direct fraud losses, surpassing traditional banking rates. High transaction volumes and easy accessibility attract both users and criminals.
Social Engineering and Account Takeover Risks
SIM-swap, credential theft, and social engineering fuel the fraud surge, exploiting user trust in daily platforms. SIM-swap investigations spiked 327% to 47 cases in 2025.
Fraud Targeting Mobile Wallets and Payment Apps
A coordinated operation involving 123,000 fraudulent SIM cards siphoned Sh500 million from the Fuliza service, proving wallet-level fraud can achieve industrial scale if unchecked.
Challenges in Monitoring High Transaction Volumes
Legacy systems operating in channel silos produce fragmented and inconsistent data, making it difficult to build a unified view of customer behavior across mobile, card, and online touchpoints.
Need for Real-Time Detection
The Central Bank of Kenya’s National Financial Inclusion Strategy 2025–2028 includes a new fraud compensation framework, signaling that reactive responses no longer satisfy regulatory standards.
How Behavioral Intelligence Improves Fraud Detection
AI-Driven Behavioral Analytics
Behavioral analytics creates unique customer profiles to detect anomalies by identifying personal pattern deviations instead of using broad thresholds. This accuracy greatly lowers false positives, improving the experience for legitimate users.
Detecting Unusual Transaction Patterns
AI and ML models featuring pattern recognition, anomaly detection, unsupervised clustering, and behavioral profiling provide risk evaluation that is real-time monitored, updated dynamically, and scalable to the increasing complexity of modern financial criminal activity.
Real-Time Customer Activity Monitoring
Institutions that embed real-time monitoring and adaptive authentication into their operating models are better positioned to protect customers without introducing friction into legitimate transactions.
Device Intelligence and Geolocation Analysis
The application of AI in banking in Kenya extends well beyond transaction screening. Device fingerprinting, geolocation consistency checks, and behavioral session analysis combine to flag account takeover attempts that transaction data alone would miss.
Automated Fraud Scoring and Escalation
AI-powered systems now achieve 90 to 99% accuracy in fraud detection, compared to traditional rule-based methods that historically produced false positive rates of 30 to 70%. Automated scoring clears routine alerts and ensures high-risk cases reach investigators without delay.
Strengthening Cybersecurity Across Mobile Banking Platforms
Multi-Factor Authentication and Biometric Security
The industry expects 30% of enterprises to consider biometric authentication unreliable in isolation due to deepfakes by 2026, pushing institutions toward layered verification that combines biometric, behavioral, and device signals simultaneously.
Secure API Integration Across Payment Systems
Cloud-native, API-first architecture enables banks to scale detection capabilities and integrate with existing technology stacks, whether on-premises, hybrid, or cloud-based. Gaps at API integration points remain a common entry vector for fraud.
Coordinated Fraud Monitoring Operations
Shared intelligence platforms and industry partnerships improve early detection of coordinated fraud campaigns that no single institution can see from its own data alone.
Incident Response and Containment
A structured incident response framework defines containment steps for each fraud typology. The time between detection and containment is the most consequential variable in limiting financial damage.
Enterprise-Wide Cybersecurity Governance
Kenya’s regulatory environment increasingly requires institutions to balance fintech innovation with cybersecurity obligations and consumer protection commitments, making governance a compliance function, not just an internal discipline.
Compliance and Operational Risk Management Priorities
AML Monitoring in Mobile Payment Systems
Increasing AML coverage in cloud environments, alongside real-time consortium learning for faster decisioning, are active priorities within Kenya’s leading financial institutions. Mobile channels present specific AML complexity due to transaction speed and the anonymity of certain transfer patterns.
Customer Data Privacy Obligations
Behavioral profiling generates rich personal data. Financial institutions must operate within Kenya’s Data Protection Act, ensuring that consent, retention, and access controls are in place before behavioral data is used for scoring.
Regulatory Oversight for Digital Financial Services
The CBK’s National Financial Inclusion Strategy 2025–2028 targets structured digital complaint channels, improved transparency, and formal fraud redress mechanisms, raising the compliance bar for every provider in the mobile payments space.
Vendor and Third-Party Risks in Payment Infrastructure
Third-party integrations are a common source of unmonitored exposure. Security obligations must be embedded into vendor contracts and reviewed regularly, not assessed once during onboarding.
Auditability and Reporting
Global regulators are placing strong emphasis on model governance and explainability, requiring AI fraud systems to align with audit frameworks and compliance reporting standards. Kenya’s CBK supervisory guidance is moving in the same direction.
Strategic Priorities for Banks, Fintech Firms, and Security Providers
Investing in AI-Powered Fraud Prevention
90% of financial institutions globally now use AI for fraud detection, while 77% of consumers expect their banks to deploy AI for fraud prevention. In Kenya’s competitive mobile banking market, this has shifted from differentiation to baseline expectation.
Building Scalable Transaction Monitoring Infrastructure
Infrastructure designed for today’s transaction volumes often cannot absorb the growth rates seen across financial technology in Kenya. Scalability planning must account for three to five-year volume projections, not current loads.
Collaboration Between Banks and Fintech Providers
SWIFT, Google Cloud, and 12 global banks are piloting federated learning to build collective fraud intelligence while ensuring data privacy. Kenya’s interconnected mobile ecosystem is ideal for this collaborative approach.
Long-Term Cybersecurity Roadmaps
The global AI fintech market is expected to grow from $17.93 billion in 2025 to $60.63 billion by 2033. This underscores that AI-driven security infrastructure requires long-term commitment, not just a single deployment.
Join Mobile Banking Security Leaders at WFIS Kenya
WFIS Kenya brings together 500+ senior technology and business leaders from leading banks, insurance providers, microfinance institutions, and fintech firms to explore the next frontier of financial services innovation. For fraud prevention practitioners and security architects, it is the region’s most concentrated forum for exchanging threat intelligence and benchmarking institutional approaches. Sessions at WFIS Kenya are at par with the world’s most insightful sessions on cybersecurity in finance expos. These sessions inform professionals how East Africa’s mobile money ecosystem can defend itself in the most efficient way. The 2027 edition is where those conversations continue.
Frequently Asked Questions
What is behavioral intelligence in mobile fraud detection?
Behavioral intelligence uses AI to build individual customer profiles and flags transactions that deviate from each user’s established normal activity patterns.
Why is mobile money fraud increasing in Kenya despite security investments?
Evolving methods like SIM swapping outpace static controls; AI adapts continuously while rules require manual updates.
What does Kenya’s regulatory environment require for fraud reporting?
CBK mandates digital complaint channels, formal redress, and improved fraud transparency.
How can smaller fintechs access AI fraud detection affordably?
Cloud-native, API-first platforms offer behavioral analytics on a usage basis without major infrastructure costs.
What is the value of a cybersecurity expo for compliance teams?
It offers threat intelligence, benchmarking, and peer learning on shared East African fraud typologies.