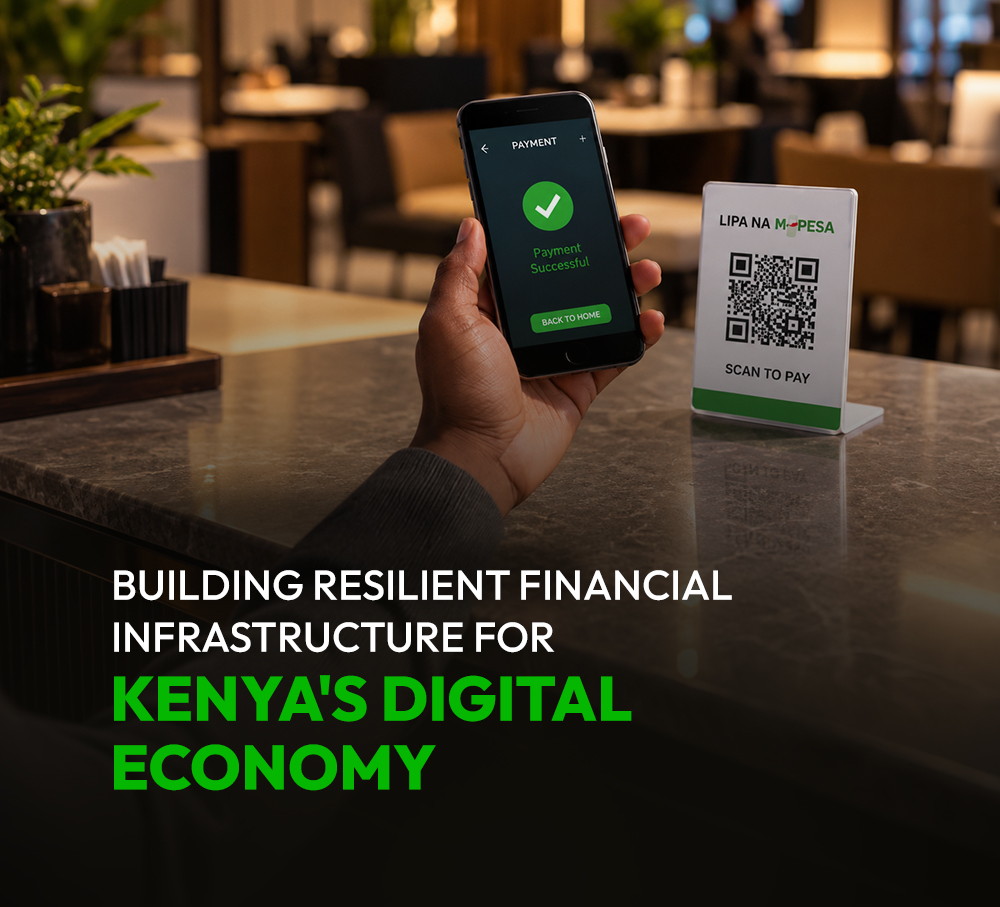
Kenya’s financial system is booming, but the technology supporting it can’t keep up. With almost everyone using mobile money (98%) and most major banking done digitally (94%), discussions about cloud banking in Kenya are now about day-to-day operations, not just strategy. Financial companies (banks, fintechs) know they must modernize. Their challenge is figuring out how to do this by moving to the cloud without putting their customers and institutions at risk.
Why Financial Infrastructure Modernization Is a Strategic Priority
Five key challenges are making it harder for Kenya’s current technology systems to keep up with its digital goals.
- Rapid expansion of digital banking services: More customers are using mobile apps and online banking (56.49% preference in 2024), and the backend capacity is falling behind this shift.
- Growth in mobile payments and financial transactions: The existing infrastructure was not designed to handle the projected $24 billion in digital payment transaction value by 2029.
- Increasing customer expectations for uninterrupted services: Failure to provide uninterrupted service, even a single payment failure during peak times, can now cause banks to lose customers.
- Rising cyber threats targeting financial institutions: Kenya recorded 2.5 billion cyber threat incidents in Q1 2025 and has been flagged as a primary cybercrime target in East Africa.
- Demand for scalable and flexible banking operations: Banks require systems that can be quickly changed and scaled, as rebuilding the entire infrastructure every few years is too costly and time-consuming.
The Role of Cloud Infrastructure in Modern Banking Operations
Successful digital transformation in Kenya makes cloud technology the foundation of banking. It is not just about moving files; it is about completely redesigning how financial services work and grow.
- Cloud-based scalability and operational flexibility: Cloud systems automatically scale capacity to handle transaction spikes, saving money by using only what is needed.
- Disaster recovery and business continuity: Cloud-based recovery can restore services in minutes rather than days, which is vital for real-time payments.
- Real-time transaction processing: The Central Bank of Kenya’s Fast Payment System enables 24/7 real-time transactions for all sectors. Reliably supporting this national architecture requires cloud-native infrastructure.
- Infrastructure redundancy and uptime reliability: Distributed workloads across multiple nodes eliminate single points of failure without a proportional increase in cost.
- API integration across banking ecosystems: Open API frameworks link core systems with fintech partners and data providers. Cloud infrastructure accelerates these integrations and simplifies long-term governance.
Strengthening Cybersecurity and Operational Resilience
Investing in infrastructure without planning for security makes the system more vulnerable to attacks. Security and infrastructure should be funded together.
- AI-driven fraud detection: Mobile banking represented 50% of the Sh1.59 billion stolen from Kenyan banks by hackers annually. Since rule-based systems fail to stop rapid, coordinated attacks, real-time behavioral AI models are now essential.
- Enterprise-wide security monitoring: A CBK CEO survey revealed that the lack of real-time security technology leaves most financial institutions vulnerable. Implementing continuous monitoring for cloud workloads, endpoints, and third-party integrations effectively mitigates this exposure.
- Cyber incident response planning: The CBK’s cybersecurity operations center provides threat intelligence and forensics, but financial institutions must develop internal capabilities rather than relying solely on the regulator.
- Data protection and access management: RBAC, MFA, and end-to-end encryption are essential foundational controls for institutions managing large volumes of customer data.
- Third-party risk management: Most Kenyan cyberattacks focus on cloud services and enterprise financial data. Consequently, vendor security must be integrated into procurement from the start rather than addressed after a breach.
Supporting Financial Inclusion Through Scalable Infrastructure
Digital channels now provide formal financial services to over 83% of Kenyan adults. Sustainable growth depends on infrastructure that serves the nation’s entire geography.
- Expanding access to digital financial services: High-volume, low-value transactions are the backbone of inclusive finance. Infrastructure must process them efficiently without degrading access for smaller-value customers.
- Supporting rural and underserved communities: Kenya’s registered mobile money agent network reached over 501,000 agents by December 2025. Each of those access points depends on consistent backend availability.
- Mobile-first banking accessibility: With 4G subscriptions at 44.2 million and growing, the mobile interface is where most Kenyans manage their financial lives. Infrastructure designed around desktop-first assumptions misses the actual market.
- Digital lending and fintech growth: Kenya attracted $638 million in startup funding in 2024, the highest in Africa, with fintech drawing 34% of debt funding. Scalable infrastructure is the foundation that the ecosystem builds on.
Strategic Priorities for BFSI Leaders and Technology Providers
- Investment in future-ready infrastructure: Modern, cloud-native frameworks enable institutions to expand capacity seamlessly. Today, any banking solution provider in Kenya must provide this as a standard requirement.
- Collaboration between banks and technology firms: An alliance between legacy institutions and providers is now standard. Formalizing shared integration reduces redundancy and accelerates delivery.
- Long-term resilience planning: Planning must cover cyber incidents, transaction surges, regulatory shifts, and market expansion together, not in separate workstreams reacting to each event individually.
- Operational efficiency through modernization: Absa Kenya reported a 21% reduction in operating expenses after automation and process redesign. Infrastructure investment, executed with discipline, produces returns that build over time.
Explore Financial Infrastructure Innovation at WFIS Kenya
The World Financial Innovation Series (WFIS) is the leading financial technology summit in Kenya’s BFSI sector, that has earned the stellar reputation of being graced by senior leaders from institutions like National Bank of Kenya, Diamond Trust Bank, Mastercard, Absa Bank Kenya, and the World Bank. WFIS connects CIOs, CTOs, regulators, and infrastructure solution providers to address the decisions shaping Kenya’s financial architecture. WFIS Kenya serves as the essential forum for organizations developing the critical infrastructure that supports Kenya’s digital economy.
Frequently Asked Questions
1. Why is cloud infrastructure a priority for Kenyan banks?
Cloud infrastructure provides the scalability and speed needed to counter real-time cyber threats and to overcome legacy hardware limits, cut operational costs, and handle surging digital and mobile transactions.
2. How does digital transformation differ from technology upgrades?
Upgrades only replace tools. Digital transformation in Kenya restructures models around cloud, APIs, and real-time data, fundamentally changing service delivery rather than just software.
3. What are the priorities for Kenyan banking solution providers?
Kenyan banking solution providers must prioritize modular integration, compliance-ready architecture, real-time transactions, and day-one security; failing to do so leaves them lagging.
4. How does infrastructure investment drive financial inclusion?
Mobile-first, real-time processing, and reliable agent networks expand digital financial access for underserved groups.
5. Who should attend the WFIS Kenya summit?
The WFIS Kenya summit is the ideal learning and networking space for financial executives, regulators, banking leaders, insurance experts, microfinance heads and providers focused on infrastructure and digital banking challenges.