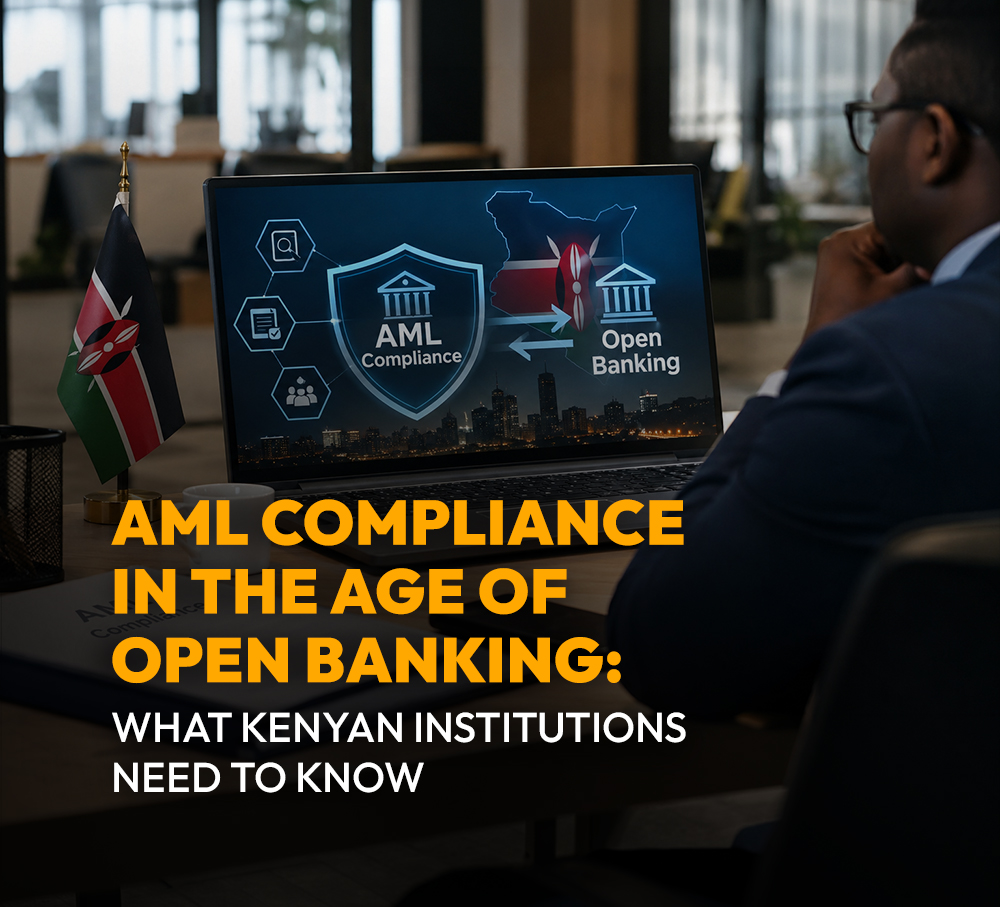
Kenya’s financial sector is entering a new phase as open banking moves from regulatory blueprint to daily practice. Banks, fintechs, and mobile money platforms are beginning to share data through secure APIs, creating a more connected banking solution that Kenyan institutions have long worked towards.
This shift brings real opportunity, but it also widens the doors through which illicit money can travel. Compliance teams, boards, and regulators now face a pressing question: how does anti-money laundering practice hold up inside an open, interconnected system built on shared data and third-party access?
The answer will shape the extent of trust that customers and international partners place in Kenya’s financial ecosystem going forward.
Understanding Open Banking in Kenya’s Financial Setting
How Open Banking Is Taking Shape
Kenya has no dedicated open banking law as of yet. Data sharing currently sits under the Data Protection Act and the National Payment System Act, with the Central Bank of Kenya steering progress through its National Payments System Vision and Strategy.
A draft framework released in March 2024 outlines API standards, OAuth-based authentication, and ISO 20022, with full compliance expected between 2026 and 2027.
What This Means for Financial Institutions
Banks, SACCOs, and fintechs are preparing to open account and transaction data to licensed third parties once customers give clear consent. This builds directly on Kenya’s mobile money history and extends the digital transformation Kenya has pursued since M-Pesa reshaped everyday payments, pushing the market towards consent-based, interoperable data sharing.
Why AML Compliance Becomes Critical Under Open Banking
New Channels, New Vulnerabilities
Each new API connection and third-party integration widens the surface area for financial crime. Funds moved across linked platforms can be layered and disguised more easily than in a single, closed system, making detection harder for institutions that still rely on siloed monitoring tools. Criminals often exploit gaps between systems rather than weaknesses within any single platform, making cross-institutional visibility essential.
Kenya’s Standing on the Global Stage
Kenya remains under increased monitoring by the Financial Action Task Force (FATF) following the mutual evaluation in 2022, leading to grey listing Kenya in February 2024. Furthermore, the European Commission formally added Kenya to its list of high-risk third-countries for Anti-Money Laundering in June 2025, intensifying scrutiny of correspondent banking relationships.
The Cost of Non Compliance
Institutions that delay strengthening controls risk administrative sanctions, strained correspondent banking ties, and reputational harm that outlasts any single enforcement action.
Key AML Regulations Kenyan Institutions Must Follow
The Legal Framework Institutions Should Know
The Proceeds of Crime and Anti-Money Laundering Act (POCAMLA) of 2009 remains Kenya’s core AML statute, reinforced by the 2023 Regulations and the 2025 Amendment Act. Additionally, the Prevention of Terrorism Act addresses counter-terrorism financing, while the Data Protection Act governs how customer data is collected during due diligence.
Together, these laws form a layered framework that supervisors expect institutions to apply consistently, not selectively.
Core Obligations for Institutions
Reporting institutions must apply risk-based customer due diligence, escalate enhanced checks for politically exposed persons and high-risk jurisdictions, promptly file Suspicious Transaction Reports (STRs) with the Financial Reporting Centre, and retain records for at least 7 years.
Cash transactions of $15,000 or more are subject to mandatory reporting. Institutions are also expected to review these thresholds periodically against updated regulatory guidance.
Practical Compliance Strategies for Open Banking Institutions
Strengthening Internal Controls
Institutions should appoint a resident senior Money Laundering Reporting Officer with direct board access and no conflicting revenue duties, keeping accountability built into governance rather than treating it as an afterthought.
Collaborating Across the Ecosystem
Banks, fintechs, and API aggregators need shared standards for identity verification and monitoring, since weak controls in an open banking chain can expose the wider network.
Investing in Technology
Modern transaction monitoring and sanctions screening tools help institutions keep pace with real-time data flows. A capable digital banking ecosystem in Kenya depends on systems that flag anomalies instantly, and the growing use of AI in banking is helping teams spot patterns humans might otherwise miss.
Challenges Kenyan Institutions Face in AML Compliance
Many institutions still struggle with fragmented beneficial ownership data, inconsistent supervision across sectors, and limited resources for continuous monitoring. Smaller SACCOs and fintechs often lack the technical capacity larger banks already have, a gap that slows the pace of digital transformation Kenya needs to sustain inclusive financial growth.
Closing this gap will likely require shared infrastructure that smaller institutions can access without bearing the full cost alone.
Secure Your Seat at WFIS Kenya and Lead the Compliance Conversation!
Financial crime prevention under open banking demands—as has been made evident throughout the blog—shared knowledge and coordinated action. The World Financial Innovation Series (WFIS) in Kenya gives compliance officers, technology providers, and institutional leaders the essential platform needed to exchange crucial, practical strategies and help shape resilient banking solutions Kenya can depend on as data sharing expands.
Sessions exploring AI in Kenyan banking will equip attendees with practical tools to detect risks earlier, helping institutions stay ahead of regulatory expectations.
Scheduled to take place on 2 March 2027 at the Edge Convention Centre, Nairobi, the platform connects regulators, bankers, and technology experts to address key compliance challenges. The event prioritizes facilitating discourse on open data to improve fraud detection, and helping institutions shift from reactive reporting to proactive prevention. It also gives smaller organizations a chance to learn effective compliance strategies from industry leaders.
Don’t miss out. Visit https://kenya.worldfis.com/ for more information.
Frequently Asked Questions
What is the link between Open Banking & AML risk in Kenya?
Open Banking broadens data-sharing channels across institutions, creating additional entry points that criminals can exploit for money laundering.
Which law governs AML compliance in Kenya?
The Proceeds of Crime and Anti-Money Laundering Act of 2009 governs compliance, supported by the 2023 Regulations and 2025 Amendment Act.
Who supervises AML compliance for banks?
The Central Bank of Kenya supervises banks, while the Financial Reporting Centre (FRC) oversees suspicious transaction reports across all regulated sectors.
Why is Kenya on the FATF grey list?
Kenya’s 2022 mutual evaluation exposed serious gaps in enforcement and prosecution, leading the Financial Action Task Force to grey-list Kenya.
How can institutions strengthen compliance under open banking?
Institutions should invest in real-time monitoring technology, appoint independent compliance officers, and strengthen collaboration across the wider financial ecosystem.